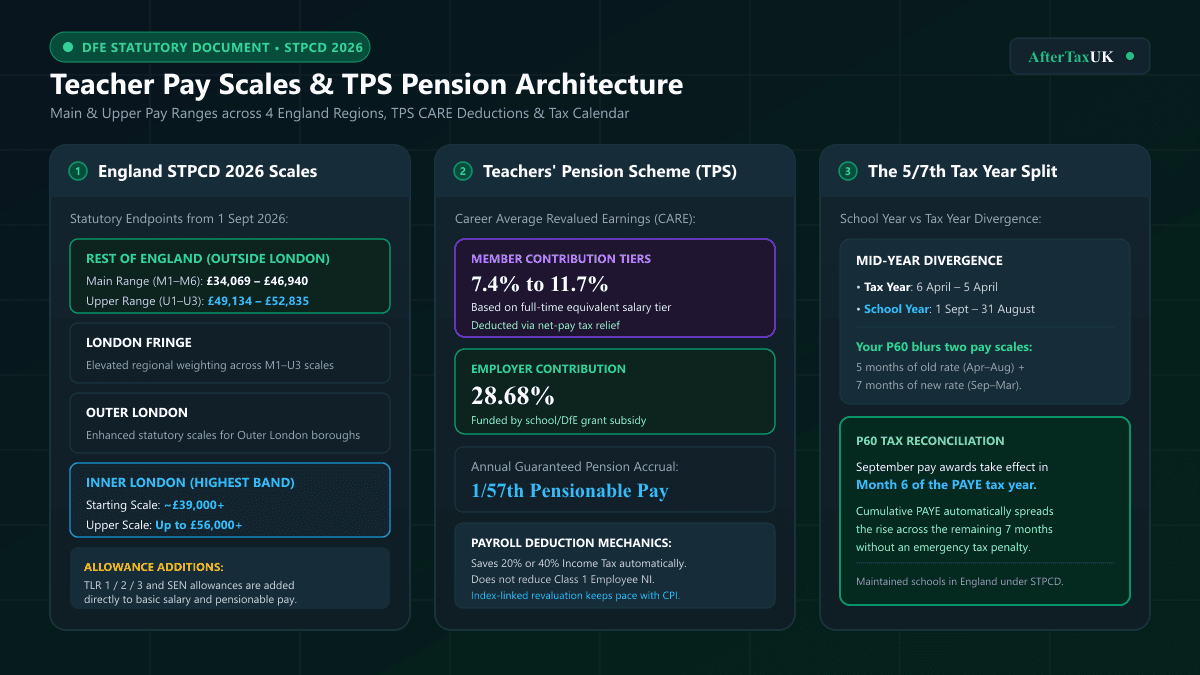
1. STPCD Advisory Pay Points (Effective 1 September 2026)
In maintained schools across England, classroom teachers progress across two core pay ranges: the Main Pay Scale (M1 to M6) and the Upper Pay Scale (U1 to U3). Under the statutory School Teachers' Pay and Conditions Document (STPCD), minimum and maximum endpoints are legally binding, while intermediate points serve as national advisory benchmarks.
Salaries vary significantly depending on school location, with higher pay awarded across the London Fringe, Outer London, and Inner London to reflect regional living and housing costs:
| Advisory Point | Rest of England | Fringe | Outer London | Inner London |
|---|---|---|---|---|
| Main Pay Scale (MPS) | ||||
| M1 | £34,069 | £35,602 | £39,196 | £41,729 |
| M2 | £36,042 | £37,647 | £41,246 | £43,713 |
| M3 | £38,400 | £39,979 | £43,403 | £45,787 |
| M4 | £40,941 | £42,513 | £45,673 | £47,961 |
| M5 | £43,529 | £45,070 | £48,438 | £50,666 |
| M6 | £46,940 | £48,479 | £52,241 | £54,131 |
| Upper Pay Scale (UPS) | ||||
| U1 | £49,134 | £50,625 | £54,047 | £59,650 |
| U2 | £50,956 | £52,442 | £56,047 | £62,581 |
| U3 | £52,835 | £54,328 | £58,120 | £64,684 |
2. Teachers' Pension Scheme (TPS) Contribution Tiers (2026/27)
The Teachers' Pension Scheme is a defined benefit Career Average Revalued Earnings (CARE) scheme. Member contribution rates are tiered according to your actual gross annual pensionable earnings:
| Tier | Annual Pensionable Earnings Band | Member Contribution Rate |
|---|---|---|
| Tier 1 | Up to £36,198.99 | 7.4% |
| Tier 2 | £36,199.00 to £48,727.99 | 8.9% |
| Tier 3 | £48,728.00 to £57,776.99 | 9.9% |
| Tier 4 | £57,777.00 to £76,572.99 | 10.5% |
| Tier 5 | £76,573.00 to £104,413.99 | 11.6% |
| Tier 6 | £104,414.00 and above | 12.0% |
Statutory Net-Pay Arrangement (Section 193 Finance Act 2004)
Teachers' Pension Scheme member contributions operate under a net-pay arrangement. This means:
- Income Tax Relief: Contributions are deducted before PAYE Income Tax is calculated, granting immediate 20% or 40% relief at source.
- National Insurance: Contributions do not reduce Class 1 National Insurance. Employee NI is calculated on your full gross salary.
- Student Loans: Student loan repayments (Plans 1, 2, 4, 5, and Postgraduate) are assessed on full gross earnings before pension deductions.
3. Illustrative Teacher Payslip Examples (2026/27)
Here is how statutory deductions look on annual earnings for standard classroom teachers in England outside London (standard tax code 1257L, standard category A employee NI):
Annual net: £26,032.40 (76.4% retention).
Annual net: £33,974.27 (72.4% retention).
4. Understanding Allowances: TLR and SEN Payments
Classroom teachers undertaking additional pastoral or curriculum responsibilities can be awarded statutory allowances that augment their base salary:
- Teaching and Learning Responsibility (TLR) Payments: Awarded for significant sustained leadership responsibilities. TLR 1 ranges from £9,272 to £15,690; TLR 2 ranges from £3,214 to £7,847; and temporary TLR 3 ranges from £639 to £3,169.
- Special Educational Needs (SEN) Allowances: Paid to classroom teachers in special schools or designated SEN posts, ranging from £2,539 to £5,008 per annum.
All TLR and SEN payments form part of your gross pensionable earnings, increasing both your monthly TPS pension contributions and your CARE pension accrual.
Explore Your Custom Teacher Pay Scenario
Whether you teach in Inner London, have a Student Loan Plan 2 deduction, or receive a TLR allowance, our dedicated teacher calculator models your exact net pay.
Estimate your teacher take-home pay nowFrequently Asked Questions: Teacher Pay & Pensions
Clear answers based on official HMRC rules and statutory guidance.
Statutory Sources & Primary Authorities
Check official government publications for the formal statutory documents: