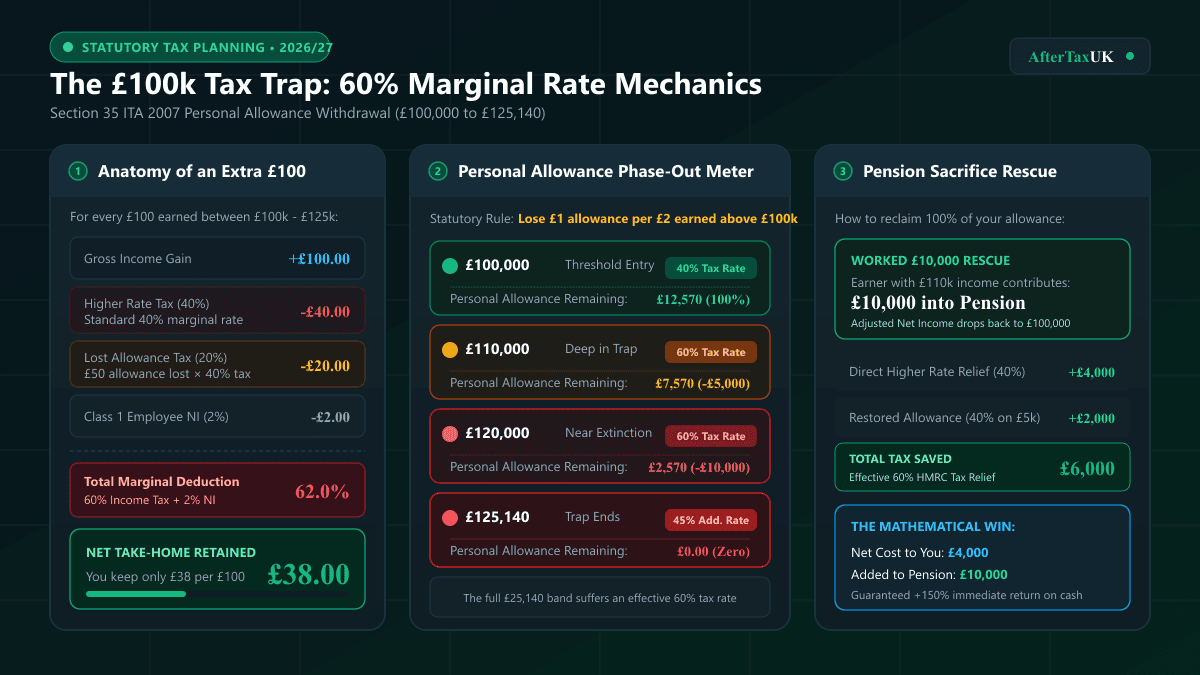
Why the marginal rate can reach 60%
For an employee in the relevant income range, an additional £100 of earnings can attract £40 of higher-rate Income Tax. It can also withdraw £50 of Personal Allowance, exposing another £50 to 40% tax: a further £20. Together that is £60 of Income Tax on the extra £100.
Employee NI can add 2% where the earnings are above the relevant upper earnings limit. That gives a 62% combined marginal deduction in this simplified employment example, before any student loan or other adjustment. It is not a 62% charge on the whole salary.
The test is adjusted net income
Salary alone is not the full test. Taxable benefits, bonuses, savings interest, dividends and other taxable income may matter. Certain qualifying pension contributions and Gift Aid reduce adjusted net income. Personal Allowance eligibility and the treatment of income types can also affect the calculation.
Scottish non-savings Income Tax uses different bands and rates, so the same 60% explanation should not be applied as a universal UK calculation. Use the Scottish calculator for an appropriate estimate.
Pension contributions need the right assumptions
Qualifying pension contributions can lower adjusted net income and may restore some allowance. Under relief at source, a £800 net payment normally becomes a £1,000 gross contribution; any further higher-rate relief must be considered through the appropriate HMRC process.
Salary sacrifice is a contractual change to pay and differs from an ordinary pension deduction. Check annual allowance, taper, the money purchase annual allowance, cash-flow needs and employer scheme rules. Pension funds are not normally immediately accessible.
Plan for the total year
Include expected bonuses, benefits and other income before selecting a contribution. Taxable car benefit, for example, can remain relevant even if an EV scheme reduces cash salary. Do not assume reducing salary to exactly £100,000 settles the adjusted-net-income test.
Use an estimate to compare scenarios, then check the source guidance and your records. Other income limits, such as childcare eligibility, are separate tests and should be checked against the relevant service rather than assumed from this calculation.
Explore the next step
Check the tool's supported scenario and assumptions before using its estimate.
Compare a pension contribution scenarioFrequently asked questions
Frequently Asked Questions
Clear answers based on official HMRC rules and statutory guidance.
Sources and further checks
Check the source that applies to your circumstances and effective period. Official guidance can change.