Start with the ownership and property type
The finance-cost restriction described here applies to relevant residential property businesses of individuals. A limited company, commercial property, mixed use or a different ownership structure can have different treatment. Establish the facts before applying a generic landlord calculation.
Rental receipts are not necessarily taxable profit. Allowable revenue expenses, ownership shares, accounting basis and the treatment of improvements or capital expenditure matter. Capital mortgage repayments are not an ordinary deductible expense.
How the finance-cost restriction works
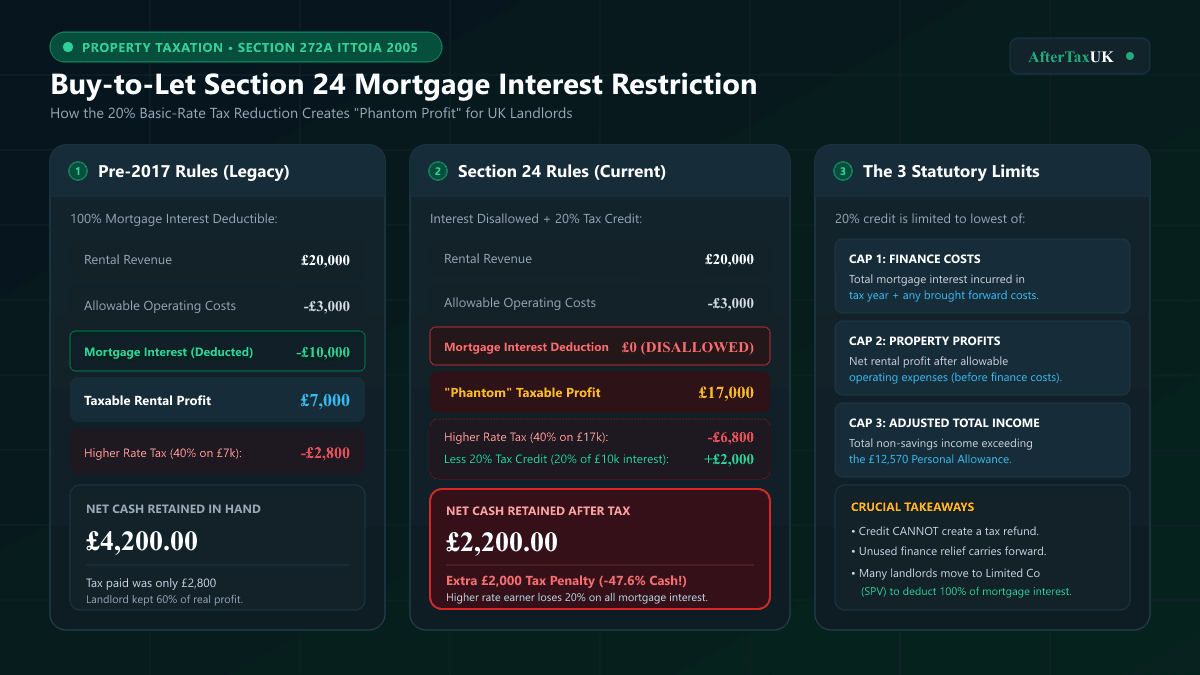
The basic-rate reduction is normally 20% of the lowest relevant amount under HMRC’s calculation: eligible finance costs, property-business profits or adjusted total income exceeding the Personal Allowance. Unused restricted finance costs may be carried forward.
It is therefore misleading to promise every landlord an immediate credit equal to 20% of all interest paid. Losses, low profits and other income can limit the current-year reduction. Read the official worked examples for the detailed ordering rules.
A simplified comparison
Suppose an individual has £12,000 rental receipts, £2,000 allowable non-finance expenses and £4,000 eligible interest. Property profit before the restricted finance-cost reduction is £10,000. If all limits permit, the interest-related basic-rate reduction would be £800.
The final tax is not calculated by simply charging one rate on the £6,000 cash surplus. Other taxable income, allowances, tax bands and the reduction limits determine the actual liability. This example excludes capital expenditure, losses and other reliefs.
Reporting and the next check
Keep records of receipts, expenses and finance costs, and check HMRC’s rules for reporting property income. Property disposals, Capital Gains Tax, Stamp Duty Land Tax and local licensing obligations are separate topics from annual rental Income Tax.
Use the rental calculator only for the supported ownership scenario and assumptions. Obtain advice where finance-cost carry-forwards, joint ownership, losses or a company comparison are material. A headline tax saving does not establish that incorporation is suitable.
Explore the next step
Check the tool's supported scenario and assumptions before using its estimate.
Estimate rental Income TaxFrequently asked questions
Frequently Asked Questions
Clear answers based on official HMRC rules and statutory guidance.
Sources and further checks
Check the source that applies to your circumstances and effective period. Official guidance can change.