Salary and dividend tax calculator UK (2026/27)
Estimate what a director-shareholder keeps from an entered salary and dividend distribution. Compare the company costs and personal deductions under the assumptions below.
Estimate salary and dividends for 2026/27
One director-shareholder, one company and a 12-month accounting period. Enter profit after other business expenses but before the director salary, employer NI and Corporation Tax.
Estimated personal monthly take-home: £4,450.31
- Director salary
- £12,570.00
- Employer NI paid by company
- £1,135.50
- Company taxable profit after salary and employer NI
- £61,294.50
- Corporation Tax
- £12,493.04
- Dividend distributed
- £48,801.46
- Retained post-tax company profit
- £0.00
- Personal Allowance after taper
- £12,570.00
- Salary Income Tax
- £0.00
- Employee NI on salary
- £0.00
- Personal dividend tax
- £7,967.77
- Personal annual take-home
- £53,403.69
Assumptions: England, Wales or Northern Ireland personal rates; standard annual director NI category; no other income, student loans, pension contributions, Employment Allowance, associated companies, brought-forward reserves or augmented-profit adjustments. Salary and employer NI are assumed deductible company expenses. Company and personal tax periods are assumed aligned for this illustration. This is an estimate, not a recommendation of an optimal salary or permission to distribute a dividend.
AfterTaxUK Editorial Team · Sources and calculation reviewed 22 October 2026
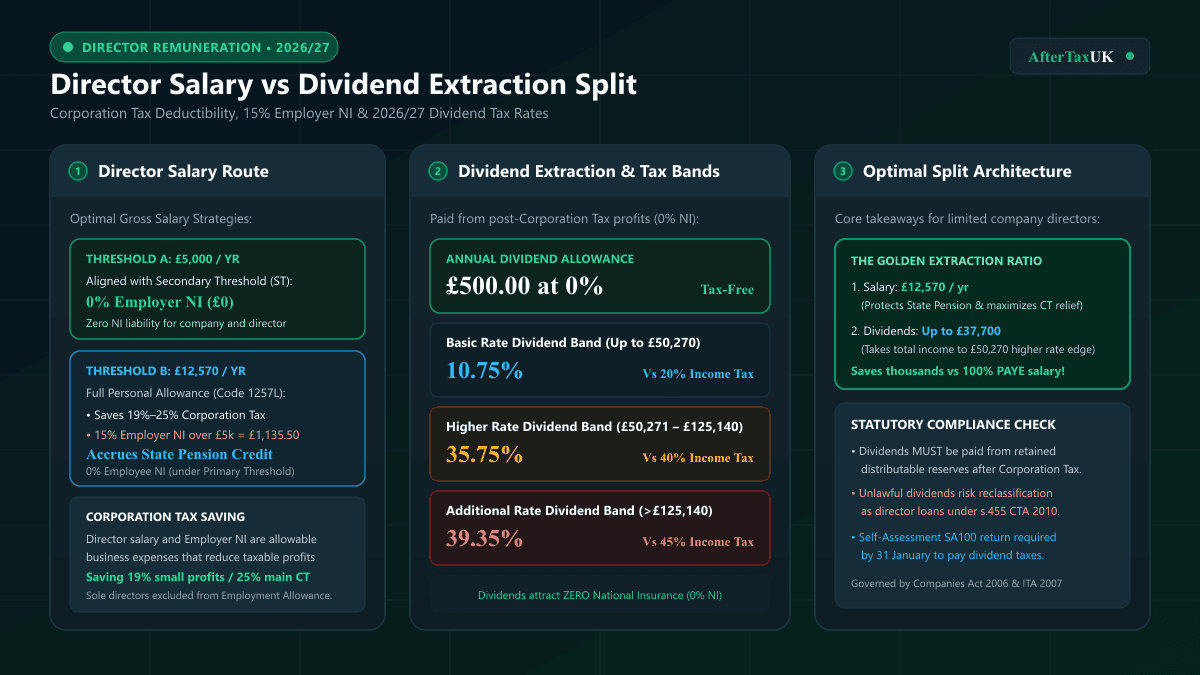
What the calculation includes
The entered company profit is before director remuneration. The tool deducts salary and employer NI, estimates Corporation Tax, and applies the distribution percentage to the remaining profit. Employer NI uses the standard 15% rate above £5,000 for 2026/27. Employment Allowance and special NI categories are excluded.
For the individual, salary is taxed before dividends. Combined salary and dividends determine the Personal Allowance taper. The £500 dividend allowance gives a zero rate on that slice while still using the income bands. Employee NI applies to salary; dividend income is not charged employee NI in this model.
Worked example: £60,000 before remuneration
With £60,000 company profit, a £12,570 salary and all remaining post-tax profit distributed, the same calculation used by the tool gives:
- Employer NI
- £1,135.50
- Company taxable profit
- £46,294.50
- Corporation Tax
- £8,795.96
- Dividend distribution
- £37,498.55
- Personal dividend tax
- £3,977.34
- Personal annual take-home
- £46,091.20
This is an annual illustration with no other income, pension or student loan. It assumes a 12-month company period aligned with the personal tax-year illustration. It does not compare every remuneration method or assess dividend legality.
Official sources and next steps
- GOV.UK: tax on dividends
- HMRC: Corporation Tax rates and marginal-relief limits
- HMRC: marginal-relief eligibility and associated companies
- HMRC: 2026/27 employer NI rates and thresholds
- Director salary and dividend guide
Director salary and dividend FAQs
Clear answers based on official HMRC rules and statutory guidance.
Recommended Resources
Related Calculators, Salaries & Guides
Explore connected UK tax tools, popular salary benchmarks, and statutory HMRC guidance.
Related Calculators
All CalculatorsTake-Home Pay Calculator
Calculate exact net salary with 2026/27 HMRC tax bands.
Hourly Wage Calculator
Convert hourly pay to weekly, monthly, and annual take-home.
Pro Rata Salary Calculator
Part-time, term-time, and holiday pay formulas for 2026/27.
Second Job Tax Calculator
Calculate take-home pay across two jobs with BR tax code.
Compare Common UK Salaries
All Salary BracketsStatutory Tax Guides & Blog
Visit Blog HubCompany and personal tax are different
Corporation Tax applies to company profits. Salary, employer NI, dividends and personal tax are separate stages; cash in a company is not automatically available as a dividend.
Associated companies and short accounting periods can reduce the small-profits and marginal-relief limits. Check distributable reserves and Employment Allowance eligibility; a sole-director-only company does not normally qualify.
Check the rules for your circumstances
Official guidance supports the rules described here; it does not approve or certify this calculator. Confirm dates, eligibility and unsupported cases before making a financial decision.