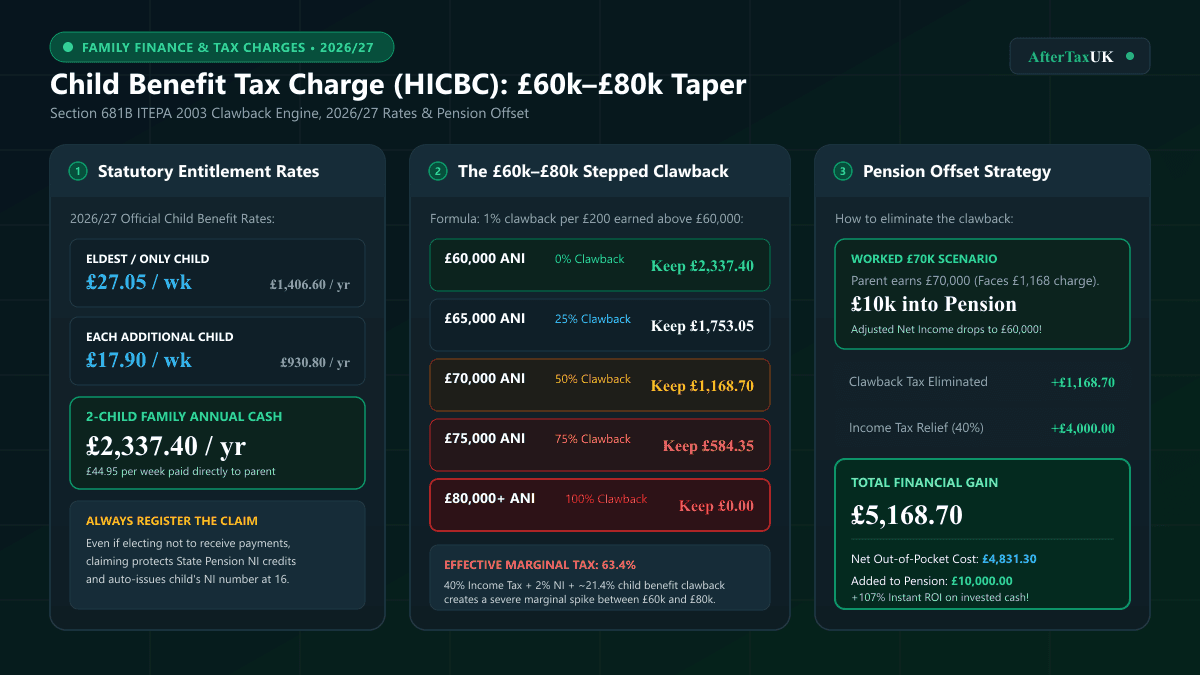
The £60,000 to £80,000 Taper Framework
Under Sections 681B–681H of the Income Tax (Earnings and Pensions) Act 2003 (as amended by Finance Act 2024 Section 15), the High Income Child Benefit Charge is calculated as follows:
Zero charge on Adjusted Net Income below £60,000. Full benefit retained.
Clawback is 1% of total Child Benefit for every £200 of ANI between £60k and £80k.
At £80,000 or above, 100% of the Child Benefit received is clawed back as tax.
- Eldest or Only Child: £27.05 per week (£1,406.60 per year).
- Each Additional Child: £17.90 per week (£930.80 per year).
- Two Children: £44.95 per week (£2,337.40 per year).
- Three Children: £62.85 per week (£3,268.20 per year).
1. How Adjusted Net Income (ANI) Is Calculated
The charge is determined by your Adjusted Net Income (ANI) under Section 58 of the Income Tax Act 2007, not simply your contractual base salary.
To calculate your ANI:
- Start with total taxable income: Gross employment earnings, bonuses, company benefits in kind (e.g. company cars), gross trading profits, savings interest, and dividends.
- Deduct allowable reliefs: Gross pension contributions (qualifying employee workplace contributions and grossed-up SIPP contributions) and gross Gift Aid charitable donations.
- The resulting figure is your Adjusted Net Income. If it is £60,000 or below, no charge is due.
2. The Pension Salary Sacrifice Strategy (Restoring £1,100+)
Because pension contributions directly reduce Adjusted Net Income, high-earning parents can achieve spectacular tax efficiency by redirecting earnings between £60,000 and £80,000 into a workplace pension or SIPP.
Consider a parent with two children earning £70,000. At £70,000, they suffer a 50% HICBC clawback (£1,168.70 charge). By sacrificing £10,000 into their pension:
| Tax & Benefit Component | Without Pension Sacrifice (£70k) | With £10k Pension Sacrifice (£60k ANI) | Net Financial Benefit |
|---|---|---|---|
| Gross Contractual Salary | £70,000.00 | £70,000.00 | — |
| Pension Contribution | £0.00 | £10,000.00 | +£10,000.00 in retirement fund |
| Adjusted Net Income (ANI) | £70,000.00 | £60,000.00 | -£10,000.00 ANI |
| Higher Rate Income Tax (40%) | -£7,892.00 | -£3,892.00 | +£4,000.00 saved (40%) |
| Employee National Insurance (2%) | -£394.60 | -£194.60 | +£200.00 saved (2%) |
| HICBC Tax Clawback (2 Kids) | -£1,168.70 (50% charge) | £0.00 (0% charge) | +£1,168.70 child benefit saved! |
| Total Statutory Savings | Baseline | £5,368.70 Combined Relief | 53.7% Effective Relief Rate! |
By sacrificing £10,000 into a pension, your net take-home cash drops by only £4,631.30 (£10,000 gross minus £4,000 tax, £200 NI, and £1,168.70 Child Benefit restored). You effectively gain a £10,000 pension asset for an out-of-pocket cost of under £4,650—an immediate 116% return on investment!
3. Claiming Child Benefit vs Opting Out of Payments
Families with income over £80,000 often mistakenly believe they should ignore Child Benefit altogether. This is a severe financial error that can permanently reduce the parent's retirement income:
Protecting State Pension National Insurance Credits
If one partner earns over £80,000 while the other takes time out of paid employment to care for children under age 12, submitting a Child Benefit claim awards the stay-at-home parent Class 3 National Insurance credits. Without this claim, they will miss qualifying years towards their full UK State Pension.
How to Opt Out of Payments
On the statutory CH2claim form or online via GOV.UK, simply select the option to "opt out of receiving payments". You gain the full National Insurance credit protection without receiving monthly funds that would trigger a Self Assessment tax return.
Model Your Pension Contribution & Take-Home Pay
Use our pension deduction calculator to see how different monthly or lump-sum pension contributions affect your net take-home pay and tax thresholds:
Open workplace pension calculatorFrequently Asked Questions: Child Benefit Tax Charge
Clear answers based on official HMRC rules and statutory guidance.