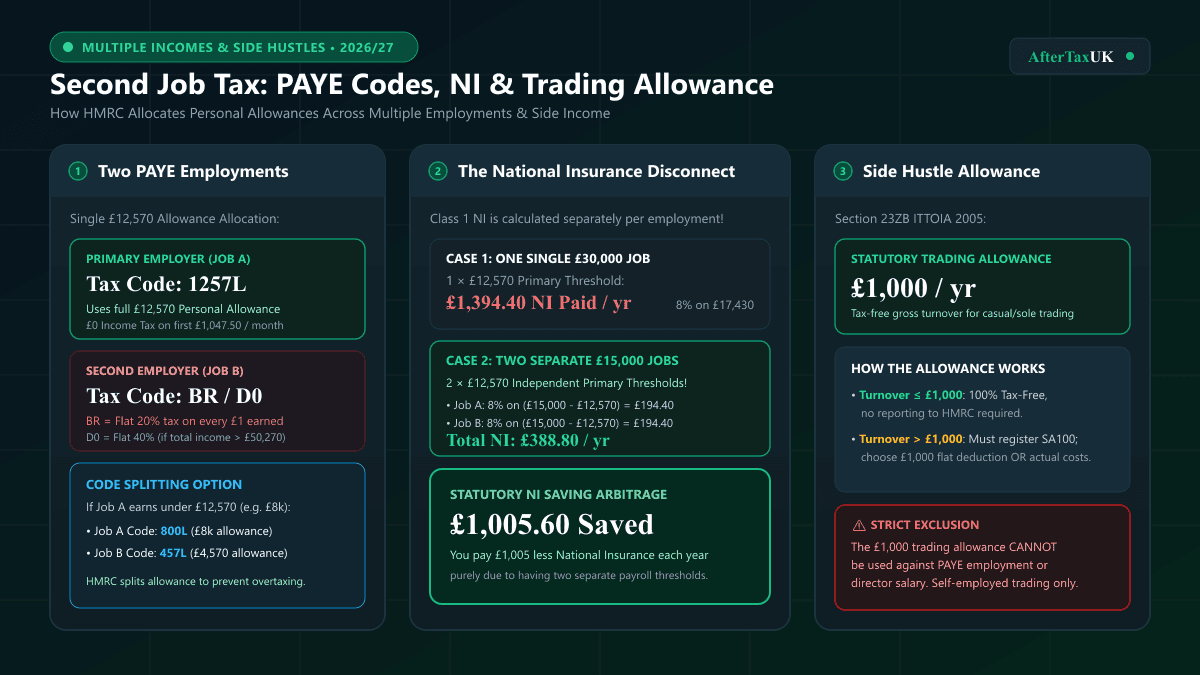
Two PAYE jobs and your allowance
You normally have one Personal Allowance for the year, allocated through your tax codes rather than a new allowance for every job. HMRC may allocate it to one source or split it where appropriate. BR is common for another job but is not correct for every person.
If combined income crosses a tax band or the allowance-taper threshold, a basic-rate deduction at one employer may not settle the final liability. Check the estimated income and tax code for both employments in your Personal Tax Account.
National Insurance is not simply combined annual tax
Employee Class 1 NI is normally calculated by each employer for its pay period. There are circumstances where earnings must be aggregated, and special arrangements can apply for employees with more than one job.
A two-job calculator can estimate a stated scenario but should explain whether it uses annual approximations and separate employment thresholds. Student-loan deductions, pensions and different NI categories can alter the payslip result.
A side business is different from a second employment
The trading allowance concerns qualifying gross trading income, not all second-job wages. If total eligible trading income is £1,000 or less in the tax year, you may not need to report it, subject to the rules and exceptions. Employment wages do not receive this allowance.
Above £1,000 gross trading income, check whether you need to register and report through Self Assessment. Using the allowance instead of actual allowable expenses is a choice with conditions; you cannot normally deduct both against the same income.
Check the full reporting requirement
Receiving PAYE income does not by itself establish whether a tax return is required. Other income, the business circumstances and a notice from HMRC can create a reporting obligation. Use the official return checker rather than a blanket salary threshold rule.
Keep separate records for wages, business receipts and expenses. Ask HMRC to correct inaccurate employment estimates and obtain advice if the activity’s employment status or reporting treatment is unclear.
Explore the next step
Check the tool's supported scenario and assumptions before using its estimate.
Estimate pay from two jobsFrequently asked questions
Frequently Asked Questions
Clear answers based on official HMRC rules and statutory guidance.
Sources and further checks
Check the source that applies to your circumstances and effective period. Official guidance can change.